The words you'll hear
Deductible
The part you pay. Some policies have a separate wind and hail deductible, sometimes a percentage of the home's insured value.
Actual cash value (ACV)
The value of the damaged roof after depreciation for age. Many insurers pay this first.
Recoverable depreciation
The rest of the replacement cost, paid after the work is done and proven, on replacement-cost policies.
Supplement
A request to add items the first estimate missed, like code-required ice barrier or decking found rotten during tear-off.
How a claim usually goes
- InspectionWe inspect and photograph the roof and tell you whether the damage looks worth filing.
- You fileYou contact your insurer, report the date of loss and get a claim number.
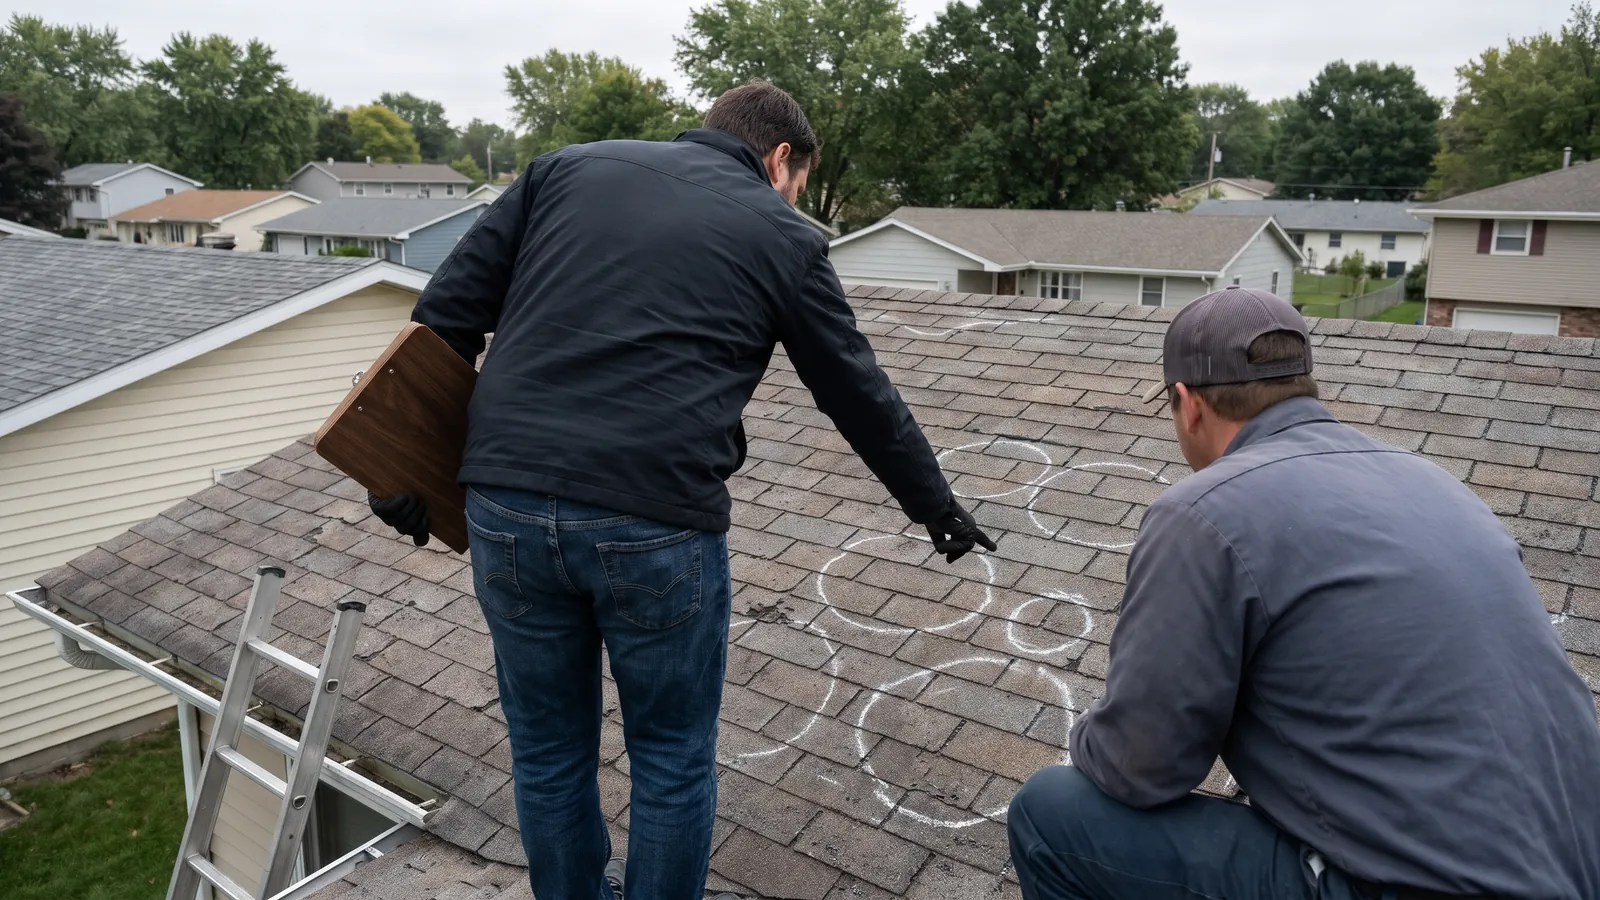
- Adjuster visitThe insurer's adjuster inspects. We're glad to meet them on the roof so nothing is missed.
- EstimateThe insurer sends a written estimate. We compare it to what we found and what code requires.
- First paymentOften the ACV, less the deductible. Mortgage companies sometimes co-sign the check.
- The workWe build the roof to the approved scope, plus any approved supplements.
- Final paymentWe send completion photos and the invoice; the insurer releases recoverable depreciation.
What a roofer can and can't do
We can document damage, meet the adjuster, explain construction and code requirements, and request supplements with photos. We can't negotiate your claim or act as your adjuster, and the decisions belong to you and your insurer.
About deductibles. Your deductible is yours to pay. Any contractor who offers to cover, rebate or hide it is misrepresenting the job to your insurer. We don't, and you shouldn't accept it from anyone.
Common questions
Will a claim raise my premium?
It can, depending on your insurer and history. That's one reason not to file for minor damage.
What if the adjuster denies damage I can see?
Ask for a re-inspection, and ask us to attend. Clear photos of a consistent hail pattern carry weight.
How long do I have to file?
Your policy says. Many require prompt notice; don't wait for a leak.
My mortgage company is on the check. Now what?
That's common. Your lender has a process for endorsing it; we can explain what they usually need.